

Daily Loan - Money Tracker
SUMMIT CITY PROSTHETICS & ORTHOTICS, INC.
- Ratings
- 4.5
- Installs
- 1,000,000+
- Category
- Finance
Daily Loan - Money Tracker analysis by Appwee
I approached Daily Loan - Money Tracker as a practical finance app rather than a complete banking replacement. Its purpose is straightforward: help me record spending, keep an eye on a budget, and make loan-related money habits easier to follow. That narrow focus is useful because it encourages a repeatable routine instead of asking me to manage every part of my financial life in one place.
The app is free, aimed at Everyone, and belongs to the finance category. It is published by SUMMIT CITY PROSTHETICS & ORTHOTICS, INC., which is an unusual developer name for a money tool and something I would personally keep in mind before making it the only place where I store important financial information. Still, the app has reached over one million installs and holds a 4.5 average from around 7,400 ratings, so it has clearly attracted a substantial audience.
My overall impression is that this works best when I treat it as a daily ledger and budget companion. It can help turn vague worries such as “I am spending too much” into visible entries and categories. It is less convincing for someone who expects automatic bank synchronization, investment analysis, shared household accounts, or a full debt-management platform. The value comes from consistent input and review, not from the app doing every financial task automatically.
How I would build a reliable daily money routine
Start with a simple baseline instead of trying to track everything
The most effective way to begin is to create a small routine around the main actions the app is designed for: logging expenses, checking the budget planner, and reviewing loan-related amounts. I would not start by entering years of old transactions. That creates a large setup task and can make the app feel like work before it becomes useful.
Instead, I would begin with the current pay period or month. I would record the money that needs to be available, identify the expenses that cannot be skipped, and then leave room for flexible spending. The important distinction is between money already committed and money that can still be chosen. A budget becomes more helpful when it answers “what can I spend today?” rather than only showing a total after the money is gone.
For everyday use, I found that the strongest habit is entering a purchase soon after it happens. A coffee, bus fare, grocery item, or small online purchase may feel too minor to matter, but several small omissions can distort the picture. If I wait until the end of the week, I have to reconstruct the details from memory, and the tracker becomes less trustworthy.
A realistic example would be a weekday lunch routine. I might record the meal immediately, assign it to the same food or dining category each time, and then check the remaining amount before buying dinner. That second step is where the app becomes more than a list of transactions. The entry changes a decision I make later in the day.
I would also keep loan payments separate from ordinary discretionary spending. A repayment is not simply another lunch or entertainment purchase; it is a commitment that should be visible before I decide how much flexible money is available. Treating it as a fixed obligation helps prevent the common mistake of planning a budget around money that is already promised elsewhere.
Use the first review to correct your own assumptions
After several days of entries, I would look for mismatches between my planned budget and actual behavior. The goal is not to punish myself for spending. The goal is to discover which estimates were unrealistic. If groceries repeatedly exceed the planned amount while transport remains below it, I can adjust the allocation rather than pretending the original plan was accurate.
This is one of the app’s practical strengths: it gives a visible place to compare intention with behavior. That only works if categories remain consistent. If I label the same kind of purchase differently every time, the totals become harder to interpret. I would choose a modest set of categories that reflects my real decisions and avoid creating a separate label for every store.
I would also avoid changing the budget every time I make an unexpected purchase. A budget should record the effect of a decision, not erase the decision. If I immediately move money between categories to make the numbers look comfortable, I lose the chance to see where the plan failed. A better approach is to leave the adjustment visible and review the pattern later.
Settings and setup choices worth checking early
The first settings I would inspect are the ones that affect how quickly I can enter an expense and how clearly I can read the resulting plan. I would check the currency or regional choices available on the device, the way dates are displayed, and any default category or budget behavior that appears during setup. These details sound minor, but a tracker becomes frustrating when every entry requires correction.
I would also decide how precise the records need to be. For a casual spending overview, whole amounts may be enough. For loan payments, recurring bills, or a tightly controlled budget, I would enter the actual amount rather than rounding. The right level of precision depends on the decision I want the app to support. Excessive detail slows the habit; too little detail makes the totals misleading.
Notifications deserve a deliberate choice if the app offers them. A reminder can help someone who regularly forgets to log purchases, but too many prompts can become background noise. I would use a reminder at a time when I naturally review my day, not at a random moment when I am busy. The best reminder is one that supports an existing routine rather than trying to create discipline by force.
I would check whether the app allows any convenient defaults for repeated entries, but I would not assume that every version includes advanced automation. The current version is 1.0.6, and I would judge it by the controls actually visible on my device rather than by expectations borrowed from larger budgeting platforms. When a setting is available, it can reduce friction; when it is not, a manual routine is still workable.
Make the budget reflect timing, not just totals
One subtle problem with budgeting is that a monthly total can look healthy while the timing of payments creates pressure. I would use the planner with payment dates in mind, especially when a loan installment or major bill arrives early in the period. Money that is technically available for the month may not be available today.
This is also why I prefer reviewing the remaining amount before a purchase instead of only checking the final monthly result. A budget can be mathematically correct and still be uncomfortable if too much spending happens before the next income arrives. The app is most useful when I use it to make short-term choices, not only to inspect the past.
Faster patterns for people who dislike bookkeeping
Experienced users do not necessarily enter more information; they reduce the number of decisions required for each entry. I would keep the category structure stable, use the same naming style, and enter purchases in a consistent order. For example, I might record the amount first, choose the category second, and add a short note only when the purchase needs explanation.
I would reserve notes for exceptions rather than writing a sentence for every transaction. A note can be valuable for a medical purchase, a one-off repair, or an unusual loan payment. It is less useful when it merely repeats the category. This keeps the record readable and makes later reviews faster.
Another efficient pattern is a two-pass routine. During the day, I would make quick entries with only the essential information. At the end of the day or week, I would review the totals and correct obvious mistakes. This is a reasonable compromise for people who cannot stop to organize every purchase perfectly, while still protecting the accuracy of the overall budget.
I would be careful with batch entry, however. Entering several transactions at once can save time, but it also increases the chance of forgetting a small cash purchase or assigning the wrong date. If I use this approach, I would check the final total against my wallet or bank balance. The tracker should be a reflection of reality, not a separate version of it.
A useful workflow for loan payments
For a loan, I would create a clear distinction between the scheduled repayment and optional extra payments. The scheduled amount belongs in the baseline plan because it is part of the commitment. An extra payment should be visible as a separate decision, since it reduces flexible money and may affect what I can afford elsewhere.
I would review the loan entry before setting the rest of the month’s spending. This reverses a common but risky order of operations. Instead of spending first and hoping the repayment fits, I would reserve the obligation and then distribute what remains. Daily Loan is more helpful for this kind of discipline than for explaining the legal or financial terms of a loan, so I would still read the lender’s own documents for details such as interest, fees, and payoff conditions.
The app can also serve as a behavioral record. If I repeatedly need to move money away from a repayment plan to cover ordinary expenses, that pattern matters. It may mean the budget is too ambitious, the income timing is awkward, or the loan obligation is taking up too much room. A tracker cannot solve that problem by itself, but it can make the conflict difficult to ignore.
Where the app reaches its limits
The biggest limitation is the amount of manual attention a money tracker requires. If I forget entries, use inconsistent categories, or stop reviewing the planner, the app cannot produce a reliable picture. People who want automatic transaction imports may prefer a banking app or a larger personal-finance service that connects directly to accounts.
I would also skip this app if I needed a complete household system with multiple users, detailed shared permissions, or sophisticated reporting. A simple tracker is often easier to maintain, but simplicity becomes a weakness when several people need to contribute to one financial plan. In that situation, a collaborative budgeting tool may be a better fit.
It is not the right choice for investment monitoring either. Tracking daily expenses and planning repayments are different tasks from analyzing portfolios, taxes, market performance, or long-term asset allocation. I would use a specialist service for those needs rather than expecting this app to become an all-purpose financial dashboard.
Privacy-conscious users should make their own comfort decision before entering sensitive information. I would avoid storing unnecessary account numbers, passwords, or identifying details in notes. A budget can usually work with categories and amounts alone. Keeping the record minimal reduces the consequences if the phone is lost or someone else gains access to it.
The developer identity also makes me cautious about relying on the app as my sole financial archive. SUMMIT CITY PROSTHETICS & ORTHOTICS, INC. is the listed developer, and that does not automatically tell me how the product should be used for long-term recordkeeping. I would keep important statements and official loan documents separately, using the app as a practical planning layer rather than the legal source of truth.
Compatibility, cost, and the decision to try it
The app is free, which lowers the barrier to testing the routine without committing money to another subscription. It supports Android 7.0 or later, so compatibility should cover many older devices as well as newer ones. The age rating is Everyone, making the presentation approachable for a broad audience, although financial responsibility still depends on the user’s habits.
Its release date is January 21, 2026, and the current version is 1.0.6. That relatively early product stage reinforces my preference for using it as a focused tracker rather than assuming it has the depth of a mature financial suite. I would install it, establish a small budget, and judge whether recording expenses feels quick enough to sustain for several weeks.
The store’s short label, “Daily Loan,” points toward repayment-oriented use, while the broader experience is more useful when loan planning sits alongside ordinary expense tracking. That combination is valuable for someone whose main concern is making repayments without losing control of daily spending. It may feel too narrow for a user whose priority is detailed cash-flow forecasting or automated account aggregation.
My verdict after using the workflow consistently
I see Daily Loan - Money Tracker as a focused, manual finance companion with a clear everyday role. Its strongest use is helping me connect three actions that are often separated: recording what I spend, checking what remains, and protecting money needed for repayments. The app does not need a long feature list to be useful if those actions are exactly what I need.
The key trade-off is simple. I get more control over how the budget is organized, but I also accept more responsibility for entering accurate information. Someone who enjoys a short daily check-in may appreciate that directness. Someone who wants the app to discover transactions automatically will probably become frustrated.
My recommendation is to start with one current budget period, a limited set of categories, and a clear separation between fixed obligations and flexible spending. Review the remaining amount before making discretionary purchases, and use weekly checks to correct your plan rather than quietly hiding overspending. Those habits reveal the app’s real value much faster than filling it with historical data.
For a free finance app with over one million installs and a 4.5 average from around 7,400 ratings, it is worth trying if your goal is a lightweight expense and loan routine. I would recommend it to a person who wants a visible, repeatable money habit. I would choose a more advanced alternative for automatic bank feeds, shared household budgeting, investment analysis, or formal loan administration. The best reason to use it is not that it replaces every financial tool, but that it makes one important daily decision easier: knowing what your money is already committed to before you spend the rest.
Gallery
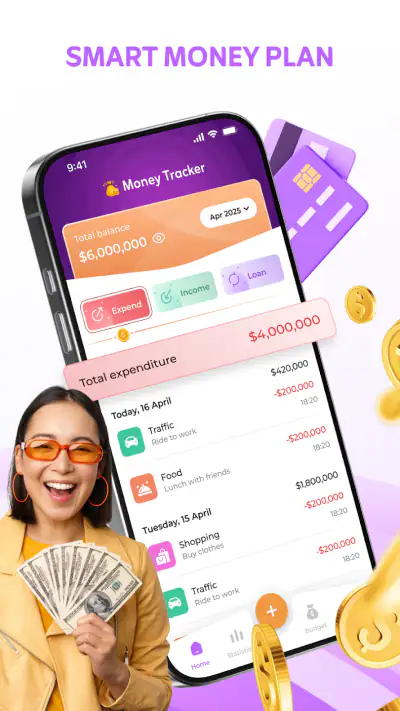
Daily Loan - Money Tracker Pros and Cons
- Simple interface for recording loans and repayments
- Helps separate personal lending from everyday expenses
- Useful reminders can reduce missed repayment dates
- Quick entries make tracking small loans less time-consuming
- Provides a private way to organize borrower information
- Requires consistent manual updates when payments are made
- May offer limited tools for complex lending arrangements
- Storing sensitive financial details may raise privacy concerns
- Not a replacement for formal loan agreements or legal records
- Some features may be restricted behind ads or in-app purchases
Daily Loan - Money Tracker Frequently Asked Questions
What is Daily Loan - Money Tracker used for?
Daily Loan - Money Tracker is designed to help users organize and monitor personal borrowing and repayment information in one place. You can typically record loan amounts, payment dates, interest or fees, and outstanding balances, making it easier to understand your daily financial commitments. It is primarily a tracking tool, not a replacement for professional financial advice or a guaranteed lending service.
Does Daily Loan - Money Tracker provide real loans or connect me with lenders?
Before downloading, it is important to understand that a loan-tracking application may only help you manage existing debts rather than provide money directly. Daily Loan - Money Tracker should not automatically be assumed to offer loans, approve applications, or connect users with licensed lenders. Carefully review the app description, developer information, permissions, and terms to confirm exactly which financial services, if any, are available in your country.
Is my financial and personal information safe in Daily Loan - Money Tracker?
Because a money tracker may contain sensitive details such as loan balances, lender names, repayment schedules, income information, or notes, privacy should be a major consideration. Check the app’s privacy policy and data-safety section before entering real information. Also review whether data is stored locally or online, whether it is shared with third parties, and whether the app supports passwords, encryption, or biometric protection.
Can I use Daily Loan - Money Tracker to calculate repayments and interest?
The app may allow users to organize repayment details and, depending on its available tools, estimate totals, interest, fees, or remaining balances. However, calculations should be checked against your official loan agreement because lenders can apply different rules, compounding methods, penalties, and payment schedules. Treat the app as a personal record-keeping aid, and do not rely on an estimate when making an important financial decision.
Is Daily Loan - Money Tracker free, and does it work on Android and iPhone?
Availability, pricing, and included features can vary by platform, country, and app version. Some functions may be free while advanced tools, advertising removal, cloud backup, or additional tracking options could require an in-app purchase or subscription. Before installing, check the current Google Play or App Store listing for supported devices, recent reviews, update history, subscription terms, and any limitations that could affect how you manage your loans.














